free esop resources
Explore our collection of resources for your upcoming ESOP in Southeast Asia.

ESOP guides for your company
Browse our free m&a templates and get familiar with disclosure letters, term sheets, and more.
Employee share option plans (or ESOPs) are a key tool for startups to incentivise staff and hire talent when funds are tight.
However, not all ESOPs are made the same. To make it easy, we’ve put together this guide to help you through the main commercial questions you need to consider. If you want some guidance on the process of adopting your ESOP, setting up the option pool, and granting options, read our guide on how to set up an ESOP.
1) how big should your pool of options be?
Usually an ESOP pool is around 7.5-15% of a company’s total shares on a fully diluted basis (10% is most common). If you are setting up an ESOP as part of a capital raising transaction, your incoming investors may have specific requirements around this.
Generally speaking, founders are expected to take on the dilution from setting up an ESOP pool, and investors are not (i.e. an investor’s agreed stake in the company is calculated on a fully diluted basis, taking the ESOP pool into account even if the ESOP has not been formally put in place yet).
This means it’s important to make sure your ESOP pool is not significantly larger than required for your foreseeable hiring needs, as that chunk of equity comes out of your own pocket as a founder. Conversely, you’ll generally want to make sure you’ve set up a big enough pool to attract and retain the talent you’ll need.
2) how much will it cost employees to exercise their options?
The exercise price is the price that an employee must pay to exercise their options and is decided on a case-by-case basis for each employee. The exercise price is often set at the market price of the company’s shares at the time the options are granted (usually determined by reference to the latest completed funding round). Employees then benefit as the value of the company increases from the date they received their options.
3) how long will employees have to exercise their options?
The expiry date of an option is the latest date by which the option holder can exercise that option. This is typically aligned with the expected time frame for the company to find an exit. Typically in Southeast Asia this will be 7-10 years from the date of grant, but of course this depends on your company’s stage and maturity.
The expiry date may change if an employee ceases to work for the company. The most employee-friendly ESOPs do not change the expiry date if any employee leaves. Leavers are therefore not forced into exercising options prior to an exit event. However, some companies prefer to give leavers a shorter time frame, for example up to one year after leaving the company to exercise any vested options. This lowers the company’s administrative burden of keeping track of departed employees who hold options.
4) what is the timetable for the options to vest?
Options almost always vest over a 3 or 4-year period. Vesting incentivises employees to stay with the company throughout the vesting period, in order to be able to exercise all of their options in the future. Generally, if an option holder leaves before the end of the vesting period, he or she will lose their unvested shares.
Our template ESOP rules allow for recipients to have personalised vesting schedules on a case-by-case basis. Shorter vesting periods may be appropriate for employees who have already worked for the company for a significant period of time prior to receiving options.
5) what happens at an exit event?
This is likely to be the part of your ESOP which requires the most thought.
Our template rules provide for single-trigger acceleration on an exit; that is, all unvested options vest on an exit event and can be exercised in full. Single trigger acceleration is the most employee-friendly position and encourages all parties to push for an exit as soon as possible.
However, potential acquirers of your company can be put off by single trigger acceleration, as they often want key employees to stay with the business after the acquisition (and the continued vesting of options encourages that). Some companies therefore prefer double trigger acceleration in order to make their company as attractive an acquisition target as possible.
We find there is a lot of variation in Southeast Asia on this point. Single trigger remains the most common, as compared to the US, where double trigger acceleration is more usual.
The different scenarios are summarised below:
| no acceleration
| None of the unvested options vest on an exit event, and any unvested options expire. Option holders can only exercise options which have vested. |
| partial acceleration
| A set percentage of the unvested options vest on an exit event. The remaining options continue to vest in accordance with the vesting schedule. This can be important to a buyer where employees remain employed by the surviving entity, so that they continue to work for the business and earn their options. However, it can be less appealing to employees, who will lose unvested options even if they are terminated without cause. |
| double trigger acceleration
| A set percentage of the unvested options vest on an exit event. The remaining options vest on a second trigger, e.g. the employee being terminated (or resigns with good reason) in connection with, and within a certain time after, the exit event. That way, if the second trigger event does not occur, the employee must stay with the company in order to earn their remaining unvested shares. However, if a buyer does not choose to keep an employee after an exit, the employee is not penalised for this. In Southeast Asia, we do not see double trigger acceleration very often but expect that to change as some of the larger tech companies adopt Silicon Valley practices. |
Despite ESOPs being a common feature of many startups in Southeast Asia, their implementation can vary according to founder and investor needs. If you would like to discuss drafting an ESOP for your own startup, you can contact us.
This short guide demonstrates how founders should calculate the number of options to include in their ESOP pool.
For the purposes of this example we have assumed that the founders are setting up a customary 10% ESOP pool (check out our guide 5 key questions when setting up an ESOP for a more detailed discussion on the appropriate size of your ESOP).
example
In almost all cases you should calculate the size of your ESOP pool on a fully diluted basis. i.e. the ESOP should be equal to 10% of all shares and options on issue (including the ESOP). Looking at a company with 1,000,000 shares on issue:

tool
If you are experiencing some arithmetic fatigue, we have you covered. Available for free download here is a spreadsheet tool that incorporates the above formula. All you need to do is plug in your total number of shares and options on issue, your ESOP pool size as a percentage, and the tool will generate the relevant number of ESOP pool shares.
Excel version
(revised 11 February 2020)
introduction
Employee share option plans (or ESOPs) are a key tool for startups to incentivise staff and hire talent.
To make it easy, we’ve put together this guide to help you through the process of adopting your ESOP, setting up your option pool, and granting options.
Related guides you might also find useful:
- 5 key commercial decisions you need to make about your ESOP before you start (a good precursor to this guide)
- Tricky clauses: what happens to an employee’s share options when a company exits?
- Tricky clauses: what is founder vesting?
Ok, let’s get started. Here are the steps that you need to take in order to set up an ESOP in your startup. This is based on industry standard for startups that have a headco and employees based in Singapore – your mileage may vary for companies domiciled in other countries.
1. draft the ESOP rules
Your ESOP rules set out the terms that apply to all options granted under the plan, including the process for granting options, how and when employees can exercise their options, and what happens to the options on an exit event, or if an employee leaves.
If you’re using our ESOP, that document will include the following schedules:
- schedule 1 – a grant letter setting out the terms of the options you want to grant to recipients
- schedule 2 – the form of the exercise notice to be delivered to the company when an option holder wants to exercise their vested options
- schedule 3 – an option certificate which records the number of options, exercise price and vesting provisions.
2. approve the rules and the option pool
Once you are happy with your ESOP rules, your directors and shareholders will need to sign some corporate approval documents to adopt the ESOP rules and set up your option pool.
For Singapore companies, these resolutions will typically be prepared by your corporate secretary. If your company is based elsewhere in Southeast Asia, we recommend confirming this step with a local law firm.
board and shareholder approval
You should ask your corporate secretary to prepare a set of directors’ resolutions in writing for the directors of your company to sign and a similar set of shareholders’ resolutions in writing for your existing shareholders to sign. The resolutions should include the following:
- approval of the ESOP rules
- the total number of options in the ESOP pool.
- authorisation for the board to grant options to recipients of their choosing (up to the number available in the ESOP pool), and
- authorization to issue shares on any exercise of the options
shareholder waivers and consents
Your constitution and shareholders’ agreement (if you have one) may include pre-emptive rights on the issue of new shares.
If this is the case, those shareholders with pre-emptive rights will need to sign a waiver in respect of any options granted under the ESOP (and any shares issued on the exercise of those options). If required, you should ask your corporate secretary to prepare this shareholders’ waiver as well.
Finally, you should also check your existing constitution and shareholders’ agreement (if any) for specific consents required from any shareholder in order to issue shares, grant options, or establish an ESOP. For instance, if you have been through an external funding round, your investor may have a veto right over the issue of any new shares or options. If that is the case, you will need that party’s written consent to grant options and issue shares under the ESOP.
Now you are ready to begin granting options.
3. grant your options
Here’s what you need to do to grant options to selected recipients.
prepare your directors’ resolutions
Each time you want to grant options, you should ask your corporate secretary to prepare a new set of directors’ resolutions in writing, approving the grant of options to a specific recipient (or list of recipients).
send each recipient their grant letter
Send each recipient:
- a completed & signed grant letter (that includes the number of options granted, the exercise price, and the vesting schedule). Our template ESOP rules include a template letter of grant at (see schedule 1) which should form the base of each grant letter.
- a copy of the ESOP rules attached (note: the schedules attached to the ESOP rules themselves should be left blank in all cases.)
If the recipient accepts the offer, they should counter-sign the letter of grant and return it to you.
issue the option certificate
Once you have received the countersigned letter, you can issue them their option certificate.
In our ESOP rules template, you can find the option certificate form in schedule 3 (again that schedule should be left blank and a separate option certificate provided to the recipient – i.e. you need to create a fresh, separate Word doc).
update your option register
Internally, you should also be keeping an option register, which is a record of all the options the company has granted, the vesting schedules, expiry dates, and exercise dates.
how can an option holder exercise their options?
If an option holder wants to exercise their options, the first thing to do is check whether those options have vested in accordance with the option holder’s vesting schedule and have not expired under the ESOP rules.
If the options have vested, the option holder should deliver an exercise notice to the company. Our template rules include a template exercise notice that can be used for this. If you’re using our template rules, the process for exercising options is set out in Rule 5.3.
summing up
Setting up an ESOP is not too difficult once you have a set of ESOP rules that you are happy with. In most cases, your company secretary will be able to prepare all the necessary resolutions pretty efficiently.
Your employer has granted you stock options as part of your remuneration package. But what does this mean when your company is sold or listed (called a liquidity event), and more importantly – when do you get your money?
In this ‘Tricky Clauses’ guide we discuss how ESOPs work for employees of startups in Southeast Asia when a liquidity event occurs.
Other installments in our Tricky Clauses series:
- Tricky clauses: warranty disclosures
- Tricky clauses: what is founder vesting?
- Tricky clauses: what you need to know about exit rights as a founder
a quick recap on ESOPs
Under an ESOP, an employee receives options over shares in a company. Those options typically vest over a period of 3-4 years.
When an option has vested, this means the employee can exercise it and purchase a share in the company. Often, employees wait for a liquidity event before exercising vested options. This is because the employee has to pay an exercise price to exercise options, and may also be liable for tax. If an employee waits until a liquidity event occurs before exercising options, they can sell the shares in that liquidity event and (ideally) get some upside after paying their exercise price and tax bill.
what is a liquidity event?
A Iiquidity event is a transaction that enables all or a substantial portion of the company’s shares to be sold. This is typically an exit transaction (i.e. a sale of the company or its assets in a private transaction) or a listing on a stock exchange.
what does a liquidity event usually mean for an employee holding options?
In Southeast Asia, employee share options often fully accelerate on a liquidity event. This means that, on an exit or a listing, all unvested options immediately vest, and employees can exercise all of their options and receive shares in the company.
Employees can then participate in that liquidity event, by selling their shares to the buyer of the company or on the stock exchange, or by receiving profits out of a sale of the company’s assets.
Under this scenario, called single trigger acceleration, employees get the chance to exercise all of their options and cash in the resulting shares, no matter how long they have been with the company. As you can see, this is an employee-friendly scenario.
what other scenarios are out there?
Another scenario you sometimes see is called ‘double trigger acceleration’
In some cases, two events need to occur before an employee gets to exercise all of their options:
- the company has a liquidity event, and
- the company or acquirer terminates the employee in close proximity to the liquidity event – (e.g. within a year).
This means that if an acquirer retains an employee, she or he can only exercise any options that have already vested, and needs to keep working at the company until the end of their vesting period before they can exercise the rest of their options. Only employees who are retrenched or made redundant soon after the liquidity event can exercise all of their unvested options (this is the second “trigger” in action).
For those employees who are retained, it is common for the acquirer to trade options in the target company for options over shares in the acquirer. This can be good for employees if the acquirer is a listed company, as it creates liquidity for the employees as options vest.
Double trigger acceleration is the most common position in Silicon Valley deals. If you’re an employee, this means you don’t automatically get to cash in when the company exits, unless the acquirer also lets you go shortly after the acquisition.
From the company’s perspective, double trigger acceleration can make the company more attractive to potential acquirers, as those acquirers will have some comfort that employees are less likely to leave soon after an acquisition.
(Confused with startup jargon? Head over to our startup glossary.)
what can companies and employees expect in the future?
Over the past year or so, we’ve seen more VC deals in Singapore adopt double-trigger acceleration, and we think we will see more of this as deals generally head towards more Silicon Valley-style terms.
Want to discuss your ESOP plan or thinking of putting one in place? Get in touch with one of our startup lawyers.
other ESOP resources for you to explore
explore our case studies
Singapore-based Pixibo provides personalised size and fit recommendations in real time for online retailers and their customers. The fashion-tech startup worked with Kindrik Partners on their recent series A raise.
We spoke to founder and CEO Rohit Kumar on Pixibo, the capital raising journey, and working with Kindrik Partners.
pixibo’s story
Rohit is an ex-Googler with experience across Europe and India, before heading to Singapore to head up operations for e-commerce advertising company Sociomantic. Between 2013 and early 2016 he launched and managed all of Sociomantic’s APAC operations and was part of the team that sold the business to dunnhumby, a Tesco company.
It was at Sociomantic that Rohit identified an issue plaguing fashion e-commerce sites. People were browsing clothes online, but very few of those visits converted into sales. “The average conversion rate is 1.5%”, says Rohit.
Pixibo’s technology was formally launched in 2018, after a few years in development. The platform makes real-time size recommendations, personalised for every shopper and for every brand and SKU. For a retailer this boosts conversion rates, reduces return rate and improves customer satisfaction. Its size recommendation engine is entirely white labelled and can be natively integrated into online stores.
“In online shopping, there’s a lot of pain points, from finding something you like, to working out which size is correct for you,” says Rohit.
“Decision fatigue can come in, reducing sales and resulting in increased return rates. The Pixibo platform works to reduce the friction felt by the consumer and the retailer.”
working with kindrik partners
“I was educating myself about series A rounds when I came across Kindrik Partners’s content online,” Rohit says.
“It was my first time doing an institutional round so I was spending more time online trying to get my head around the legal terminology and the types of things that show up. Drag alongs, tag alongs, liquidation preference clauses. There’s a lot to understand.”
(confused? see our startup glossary )
“It looked like Kindrik Partners were the best lawyers for startups,” says Rohit.
“It was clear from the content that was available online that it was their area of expertise. When I eventually needed to bring in a lawyer to help with my round, I reached out.”
on the series A round
Pixibo already had several angel investors prior to their series A round in 2018, but the startup did not have any VCs on board, so the experience was new.
“We had VPs from Google who invested at an early stage, as well as strong private angel investors. But this was the first institutional round, and it felt very different.”
A big learning was how much longer the process took. “I thought you’d just go out to market, pitch, and then get them to sign. I eventually came to understand the level of process that institutional investors require, and how this stretches out the timeline.”
“There’s a great level of detail required. From investor interest to the term sheet to drafting the shareholder’s agreement, share subscription agreement and the whole nine yards, to signing, to getting money in the bank… it can take a long time!”
Fortunately, runway was less of a concern for Pixibo. “We weren’t in a rush. We had revenue, so there was no immediate need to get funding in”, says Rohit. “We already had a recurring revenue from our licence fees we were charging. That started conversations for us with investors, too.”
working with kindrik partners
Rohit found working with Kindrik Partners and partner Lee Bagshaw provided a lot of value during the capital raising process.
“Working with Lee was great. He was very responsive to my requests and concerns and was always happy to get on a call if need be to walk through things with me.”
Kindrik Partners’s experience in capital raising in Southeast Asia was also an asset to Pixibo.
“As a first time founder, sometimes you’re like wait, hang on, why is that in there? Lee was invaluable in these situations. He understood what terms were negotiable and what terms weren’t, and was instrumental during all of the back and forth with investors.”
tips for founders embarking on their A round
Rohit has a few tips for those entrepreneurs who are considering going out to do their series A round.
- start out 6 -8 months before you need the capital: especially if it’s your first institutional round (it gets easier with a follow-on round, because you’ll have existing investors to help you get your foot in the door).
- consider a rolling close: since you’re looking for investors who are the right fit in a long-term partnership, having a rolling close allowed Pixibo to get the money in the bank from the investors who were committed, while continuing to find the perfect fit to close out our round.
- beware the temptation to think that any money will do: in the beginning, the temptation is to look for anyone with a cheque book, but then you get smarter. Find the VC’s thesis and their sweet spot, and get smarter at looking at their portfolio to see if you fit in. Who will be interested in your story?
- don’t raise too soon: Traction is important. Wait until you’re in a strong position to raise, if you can. In our case, as we’re B2B, we had clear proof points that our product works, solves a real problem for online retailers and that they are willing to pay us for it. Investors will want to see that you have put in the hard work and that capital will accelerate growth.
- have a plan for the money. You have to articulate why you need capital now, and how it will help your business.
what’s to come for pixibo
The future is bright for Pixibo, and Rohit is looking ahead to expand into new markets. “The most exciting thing about us is that we’re location agnostic. The problems retailers have in Singapore are the same ones that they have in Sydney. The opportunity is massive.”
[Note: The firm’s name was changed to Kindrik Partners in July 2020 and references to the firm’s previous name have been updated.]
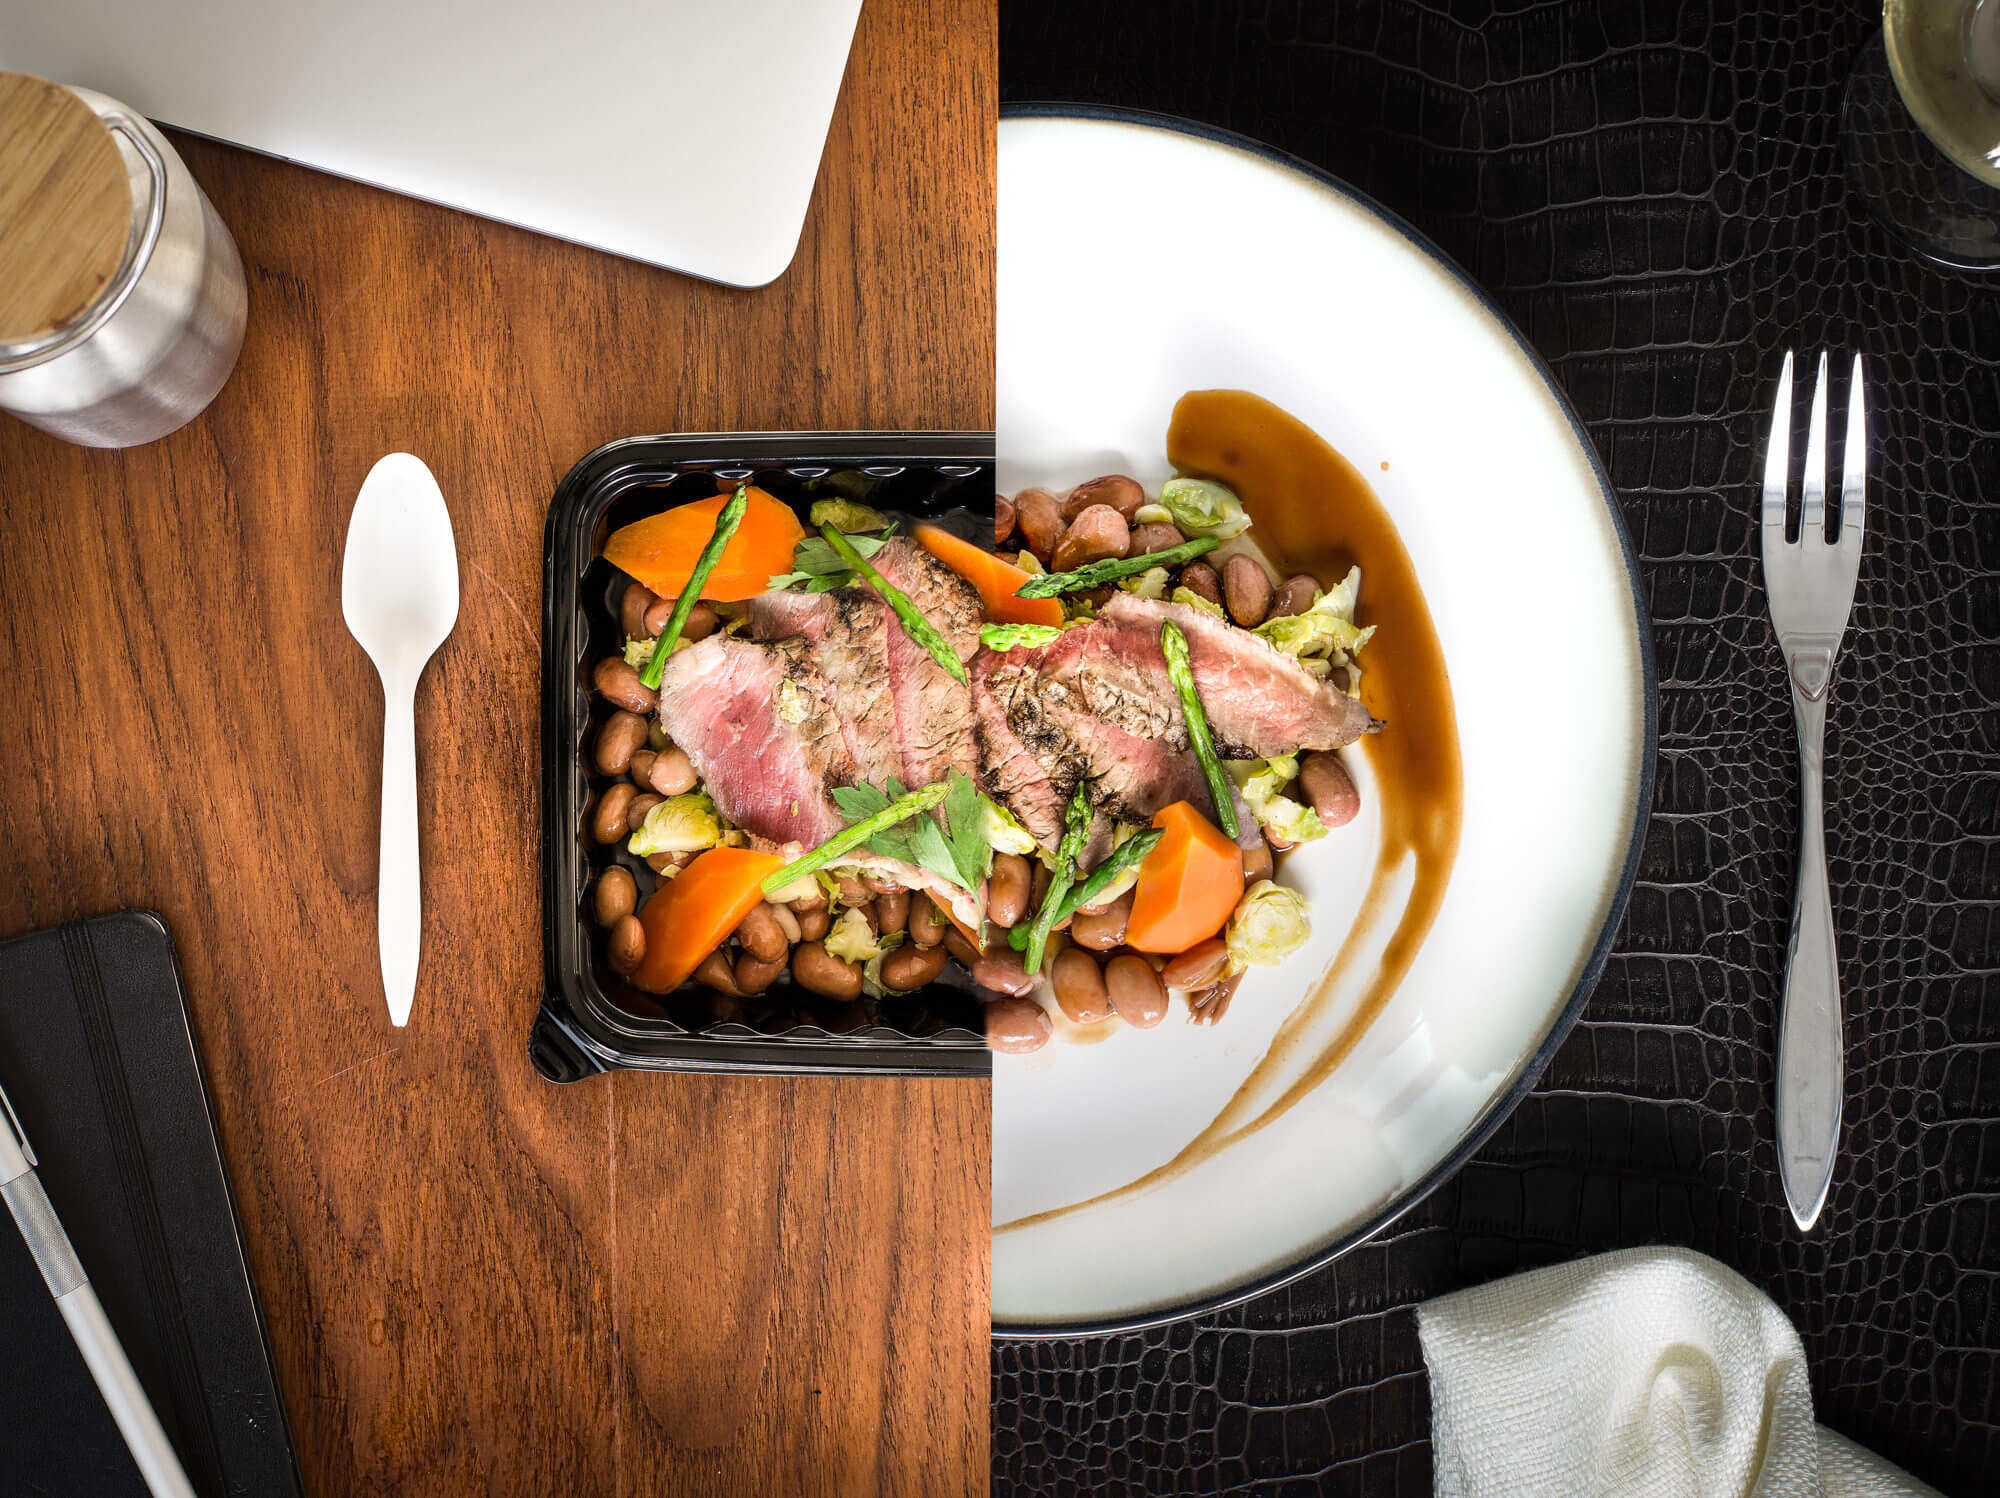
Singapore based and venture backed food technology startup Grain has fed thousands of happy customers delicious and wholesome meals, delivered in a few simple clicks.
Yi Sung Yong, Co-founder and Head of Product, recently talked to Kindrik Partners about his company and how he has found working with Kindrik Partners on their first capital raise.
the grain story
With backgrounds in management consulting and previous experience in IT startups, the 4 founders of Grain (Sung, Rifeng Gao, Isaac Tam and Ernest Sim, all recently named in the Forbes Asia 30 under 30 list) wanted to start a new and ambitious business in 2014, so they settled on changing the future of food delivery.
Since its recent beginnings, Grain is now described as a restaurant in the cloud and Uber for food in Singapore. It provides a convenient web and app delivery service for affordable and tasty food that is also good for you, offering 4 different meals each day which rotate weekly. Customers in the busy Singapore areas don’t pay for delivery and have no minimum spend.
After securing significant Series A funding, they now have major plans to offer more meals, improve operational efficiency by adding mobile distribution hub vans, increase headcount namely on the developer side and eventually to expand the business into China, including Hong Kong, and also Indonesia.
challenges
Sung says that given the diversity of food and size of the global industry, competition in the food market is building but there is still plenty of opportunity in the market. Whilst food delivery giant Food Panda largely dominates the South East Asian food delivery scene, acting as a middleman between restaurants and hungry consumers, Grain differentiates itself by offering a complete full stack food service. The entire supply chain is produced and controlled by them from one Singapore site, from the website and app business to cooking and delivery.
He also notes that whilst establishing a business and raising funds can be stressful, post-funding, hiring, onboarding and ongoing people management is their biggest challenge as they continue to grow.
working with kindrik partners
Sung’s previous experience of lawyers was that they were slow moving and traditional type lawyers that did not understand the pace of startup life.
For their first capital raise, Grain were referred to Kindrik Partners partner Lee Bagshaw through 500 Startups managing partner Khailee Ng, along with another Singaporean law firm. The referral happened on a Thursday, Lee got in touch immediately via WhatsApp and the term sheet was ready to go on the Friday. Grain did not receive a response from the other firm until the following Monday at which point the deal was well and truly on its way.
Sung says that it was Kindrik Partners’s speed and execution, WhatsApp versus long emails, moving like a startup that impressed him the most.
Kindrik Partners went on to assist Grain implement several convertible notes to secure short term bridge financing and raise of SG$2,500,000 for their Series A funding round, including investment from NSI Ventures, 500 Startups, Digital Media Partners and Ivan Lee (who founded and sold Thai Express in Singapore).
In addition to maintaining the startup pace and charging extremely reasonable legal fees, Sung really appreciated that Kindrik Partners drafted the documents from a founder’s versus lawyer’s perspective, ensuring the documents reflected Grain’s commercial motives without overkill on the legal jargon; Lee just got everything we thought we required and also pointed out the things we didn’t know we needed.
summing up
Given Grain have already delivered over 100,000 meals to ravenous Singapore residents alone, it’s looking likely that this startup will continue to eat up the market. Kindrik Partners will certainly be ready to move at speed for what seems like an inevitable growth and success.
Explore Grain.
[Note: The firm’s name was changed to Kindrik Partners in July 2020 and references to the firm’s previous name have been updated.]
about Singapore Tourism Accelerator
The Singapore Tourism Accelerator is an equity-free 6-month programme for promising technology companies that power the travel and tourism industry. The Accelerator is organised by the Singapore Tourism Board (STB) and is managed by its appointed Corporate Innovation partner, Found8.
The cohort companies undergo a three-month accelerator program where they participate in capacity- building workshops providing insights to the Singapore ecosystem and market as well as the tourism and hospitality industry. The program is tailored to support the startups in identifying and securing a pilot partner and project to testbed their solution with. This is followed by three months of pilot implementation and execution with one of the close to 30 industry partners participating in the programme – including Singapore Airlines, Changi Airport, Marina Bay Sands, and other prominent tourism brands.
The Accelerator provides founders with an opportunity to learn critical market entry skills, pilot design and implementation skills, and fundraising strategies. The programme also offers 1:1 mentoring, expert feedback, and access to industry events. The accelerator culminates in a Demo Day attended by investors and members of the tourism industry.
The Accelerator is currently running its second cohort of 10 companies and Kindrik Partners has worked with the program as an advisor for both. Particularly in the case of startups who have come from outside the region, that can include incorporation in Singapore with a view to getting investment.
pivoting to remote-first with COVID-19
With the second cohort set to begin just as the COVID-19 situation was escalating in Singapore, the decision was made to pivot from an onsite programme to a digital-first programme.
“The global health crisis put a lot of different challenges on top of everyone’s normal workload. Now that we’re split across seven different time-zones, it’s a big ask in terms of flexibility and adaptability for the people who run the workshops. We are all now masters of Zoom,” says Katrin Miller, program manager.
kindrik partners support
presentations and office hours
In line with the move to remote-first, Sarah Yen, senior solicitor at Kindrik Partners, presented to the second cohort via webinar, covering basic corporate and commercial topics such as seed rounds and other common legal issues for growth stage companies.
The startups were also able to book one-on-one Zoom legal consultations to address any queries not covered in the presentations.
“It was beneficial to the startups to know they had access to a lawyer to address more specific questions once they were further through the process”, says Katrin.
“Throughout the programme, Sarah has been stellar to deal with. She has always made herself available to our startups and the advice she gives to help the founders is always well structured and clear.”
online templates
Founder in each cohort also have access to over 30 free legal templates and guides for startups that have been tailored to building tech companies in Southeast Asia.
“Anytime one of the startups needed a template, I always consulted the Kindrik Partners database first to see if there was something they could start working from,” says Katrin.
The templates cover common corporate and commercial agreements and resolutions used by growth startups. These include founder agreements, NDAs, and sample term sheets.
support tailored for the programme
Given the industry connections that the Accelerator offers to industry heavyweights like Singapore Airlines, Changi Airport, and Marina Bay Sands, Kindrik Partners also provides targeted assistance on pilot agreements.
“Running a pilot programme is a great way to fine-tune a solution and to approach enterprise customers”, says Sarah. “However, since there’s no real uniformity to pilot agreements, founders need to be aware of some key provisions that will shape their experience with the organisation they’re dealing with.”
Katrin agrees, adding “Some corporate partners have existing documentation around pilot programmes – but for many, it’s up to the startup to set up a legal document that seals the partnership. Kindrik Partners provided real value in educating the startups and help them understand the legalese – whether it be a letter of intent, an MOU, or formal partnership agreement.”
after demo day
fixed fees on seed funding rounds
Following demo day, Kindrik Partners is available to the cohort companies to assist them with their first institutional funding rounds. To bring more transparency to the market around legal costs, Kindrik Partners offers fixed fees for institutional seed funding rounds and some associated projects, such as ESOPs.
“We want to help founders understand the terms on which they are raising their first formal funding, to help them close the deal as efficiently as possible, and of course to ensure they are getting market terms. Providing fixed fees removes one of the biggest obstacles to start-ups engaging counsel during the funding process, i.e. concerns around creeping costs and their lawyers running the clock on each call or email query”, partner Chris Wilson says.
final words
The mentorship and guidance given to the startups has been highly valued by founders in the accelerator programme.
“It’s been a hard time to run a tourism accelerator during the coronavirus pandemic – it’s no surprise that we are the hardest hit. But we’ve noticed that many of our industry partners have stepped up and focused on innovation to give them a competitive edge when the industry recovers.”
“Having Kindrik Partners on hand to assist has been truly valuable throughout the course of the programme as our founders navigate the new normal.”
